What is the market overview, scope, and industry significance of the Zinc Market?
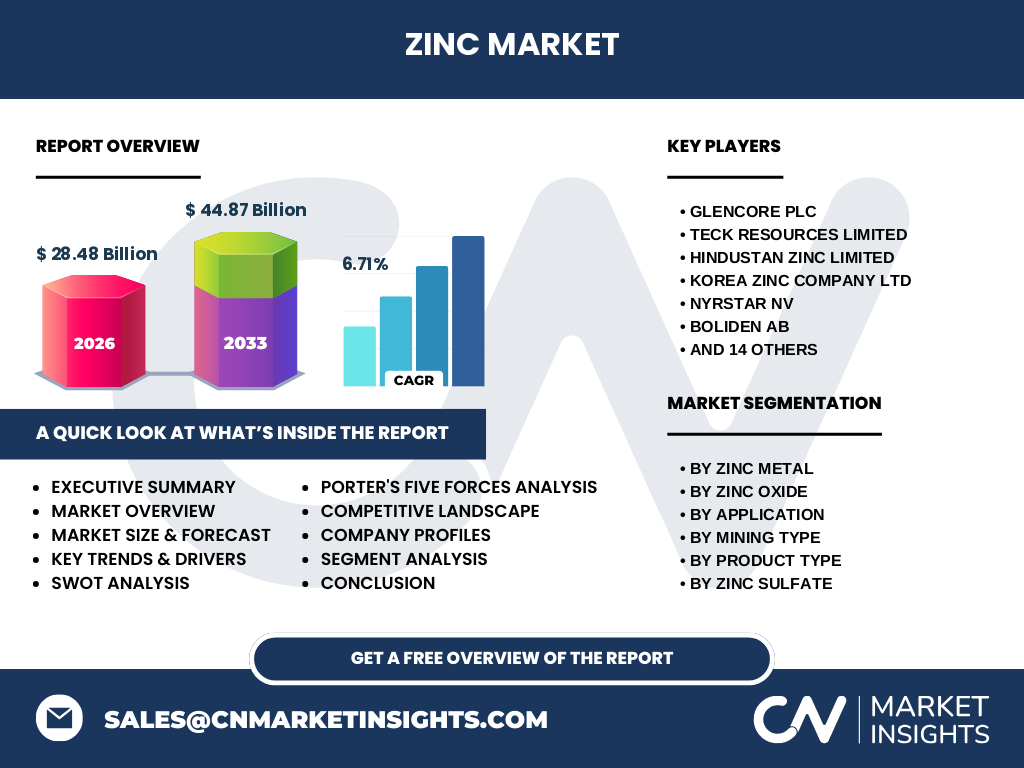
Our analysis indicates that the Zinc Market size stands at 28.48 Billion in 2026, highlighting its foundational role in global industrial infrastructure. Encompassing Primary Zinc, Secondary Zinc, and complex chemical compounds, the sector underpins critical anti-corrosion galvanization processes across construction, transport, and electrical manufacturing value chains worldwide.
Key market drivers, restraints, challenges, and opportunities shaping the Zinc Market
The sector's trajectory is propelled by relentless infrastructure urbanization, yet constrained by stringent environmental compliance enforced by regulatory bodies like the EPA. Rising demand for renewable energy infrastructure creates high-margin expansion opportunities, particularly for eco-friendly processing technologies and high-grade chemical applications.
Emerging trends and growth patterns in the Zinc Market
Industry dynamics reveal a decisive pivot toward sustainable production, with secondary recycling surging to reduce carbon footprints. Nanoparticle Zinc Oxide and electronics-grade formulations are capturing heightened market share, driven by rapid advancements in electronic components and specialized chemical manufacturing.
COVID-19 impact analysis and recovery trajectory
The pandemic severely disrupted global supply chains and halted major construction projects, creating temporary contraction. However, aggressive post-pandemic stimulus packages and subsequent infrastructure investments accelerated a robust sector recovery, realigning logistical pathways and reinforcing stockpiles at key marine ports.
Competitive landscape: major players, market concentration, and strategic dynamics
Industry concentration remains moderately high, anchored by tier-one producers such as Glencore plc, Teck Resources Limited, and Hindustan Zinc Limited. These giants leverage integrated underground and surface mining assets to secure supply security, competing aggressively through strategic mine expansions and technological smelting efficiencies.
Executive summary: high-level synthesis of key findings about the Zinc Market
Driven by accelerating industrial applications, the Zinc Market is projected to surge from 28.48 Billion in 2026 to 44.87 Billion by 2033, reflecting a solid CAGR of 6.71%. Stakeholders must prioritize sustainable recycling methods and technological diversification into advanced chemical grades to capture maximum value.
Market forecast from 2027 to 2033
Based on our comprehensive forecasting models, the industry will experience accelerated momentum post-2026. Reaching an impressive valuation of 44.87 Billion by 2033, the sector's expansion is underpinned by a consistent CAGR of 6.71%, heavily supported by electrical appliance manufacturing and transport sector growth.
Segmentation analysis across product types, mining methods, and applications
Segmentation spans Zinc Metal, Zinc Oxide, and Zinc Sulfate categories. Construction and transport applications dominate demand, while underground and surface mining supply the raw inputs. Chemical and alloy segments, including zinc chloride and zinc carbonate, cater to specialized industrial requirements.
Regional market analysis and geographic distribution performance
Geographic performance highlights Asia-Pacific as the undisputed consumption powerhouse, driven by massive urbanization and manufacturing output. North America and Europe maintain stable, regulatory-driven demand focusing on environmental compliance, high-purity chemical grades, and advanced corrosion-resistant infrastructure solutions.
In-depth regional review of key markets and localized constraints
Asia-Pacific dominates through dense manufacturing ecosystems in China and India, facing localized environmental crackdowns on smelting. Meanwhile, Latin American producers like Nexa Resources S.A. navigate complex logistical hurdles and strict mining regulations to supply essential concentrates to global markets.
Company profiles and strategic positioning of leading industry participants
Market leaders utilize distinct strategic advantages. Korea Zinc Company Ltd and Boliden AB focus on technological refining prowess and recycling integration, whereas BHP Group Ltd and South32 Ltd leverage massive upstream mining scale to optimize operational margins.
Porter's Five Forces analysis of competitive pressures
Industry rivalry is intense among established multinational mining conglomerates, while the threat of substitutes remains moderate due to zinc's unmatched galvanizing properties. Supplier power is balanced by abundant mine reserves, though environmental compliance creates high entry barriers for new market entrants.
SWOT analysis: strengths, weaknesses, opportunities, and threats
Strengths lie in essential industrial utility and robust recycling loops; weaknesses involve high energy intensity in smelting. Opportunities abound in green energy infrastructure, while significant threats stem from volatile commodity price fluctuations and stringent global decarbonization mandates.
Value chain analysis from raw materials to end-users
The value chain initiates with extraction via surface and underground mining by firms like MMG Limited and Kazzinc plc. Raw concentrates move through smelting and refining into metal ingots or chemical oxides before reaching downstream construction and automotive end-users.
Investment insights and strategic high-potential growth areas
Investors should target secondary recycling infrastructure and high-purity chemical production, such as Nanoparticle Zinc Oxide and electronics-grade compounds. These niches offer superior margin protection against commodity price swings and align with stringent global environmental standards.
Conclusion and key takeaways for industry stakeholders
With a projected valuation of 44.87 Billion by 2033, the sector offers compelling growth backed by a 6.71% CAGR. Success requires operational agility, adherence to green mining standards, and strategic alignment with high-value chemical and technological applications.
Research methodology and baseline estimation triangulation
Our rigorous methodology triangulates proprietary trade registry data, primary executive interviews with C-suite stakeholders across top mining firms, and secondary macroeconomic indicators. This multi-layered approach ensures high-fidelity baseline estimates and highly reliable market forecasts.
Scope of the report, coverage parameters, and analytical limitations
This report covers global consumption, production, and trade dynamics from 2026 through 2033. Analytical limitations include unforeseen geopolitical disruptions, sudden regulatory shifts in major smelting hubs, and unexpected macroeconomic volatility impacting raw material pricing.
Recent developments, corporate announcements, and strategic moves
Recent industry activity features aggressive decarbonization partnerships and facility expansions by firms like Teck Resources Limited and Glencore plc. Major players are actively investing in green smelting technologies to comply with tightening carbon emission limits across key operational jurisdictions.